By Viktor Yoshimura – 1st October 2026
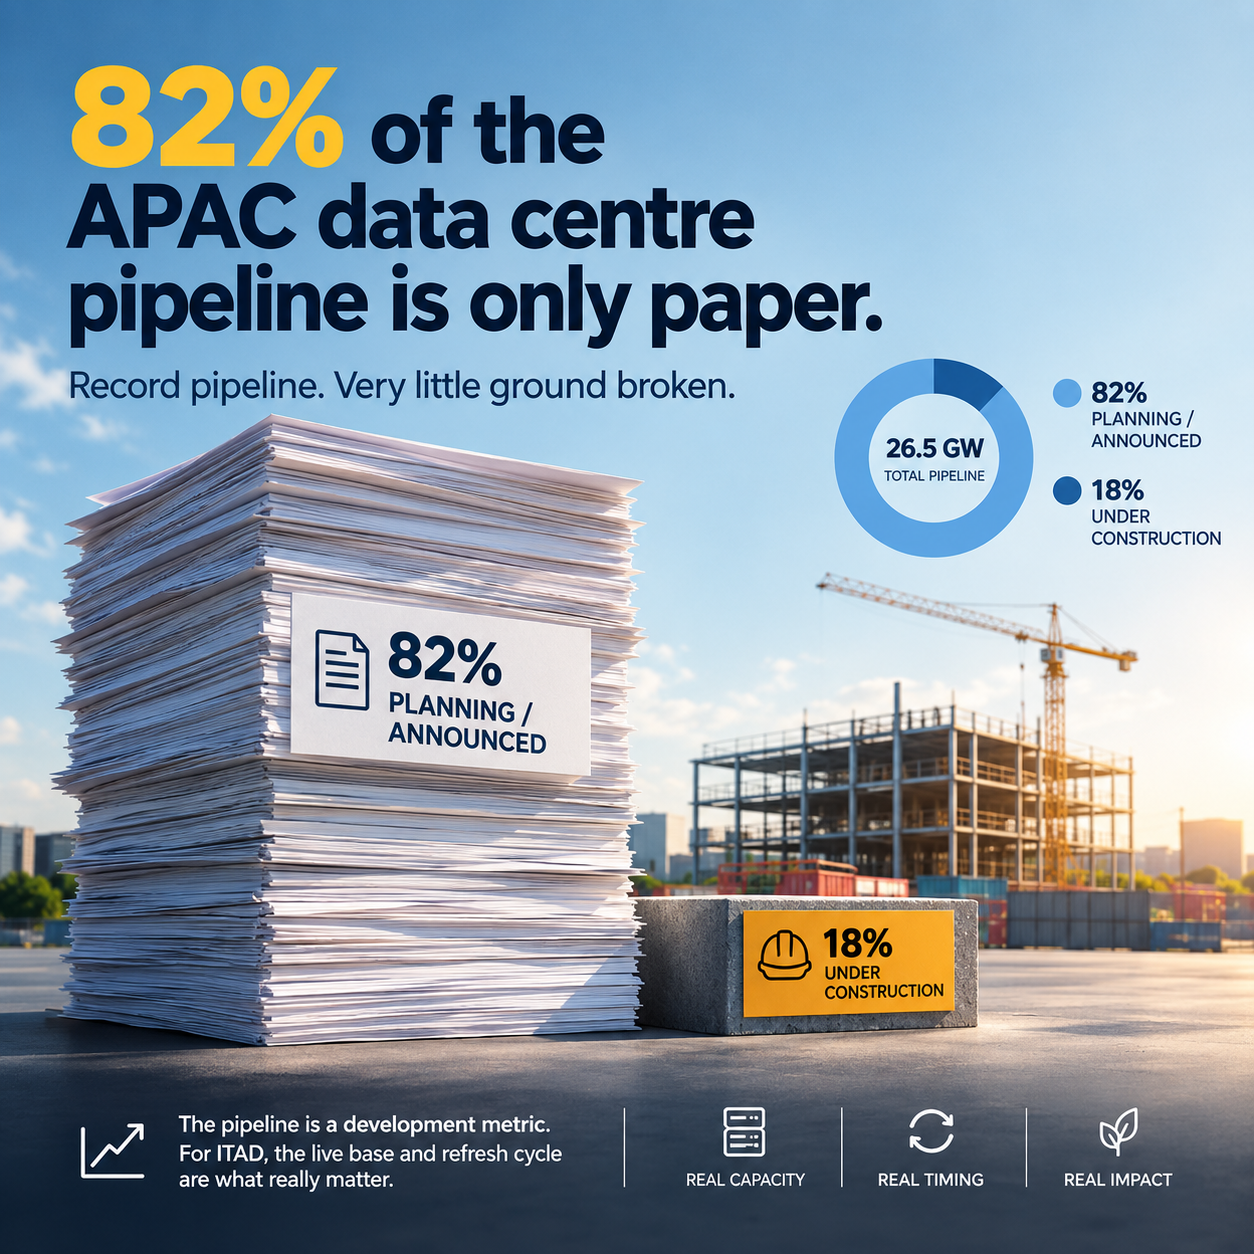
Asia-Pacific announced a record data centre pipeline this year. For anyone downstream, reading it as future volume is the most expensive mistake on the table.
Cushman & Wakefield put the Asia-Pacific data centre pipeline at 26,455 MW in its H1 2026 update, a record, up 7,103 MW in six months. The figure was repeated everywhere, and it is correct. As a guide to anything that happens downstream, it is also close to useless.
Of that record, 4,764 MW (18%) is under construction. The other 21,691 MW (82 percent), is in planning only, with no ground broken. That is a planned-to-building ratio of 4.5 to one. Capacity actually delivered into operation over the half was about 1,372 MW, so the pipeline grew roughly five times faster than it converted. A number that grows five times faster than it converts is a measure of intent, not a forecast, and none of this is a criticism of the data, which states the split plainly. The problem is entirely about how the headline gets used.
The number nobody publishes
For ITAD, reverse logistics and asset recovery, the pipeline is the wrong number regardless of how much of it is real. Hardware retires from capacity that exists, not from capacity announced, and not from capacity under construction. The figure that governs future decommissioning volume is the live operating base, and no analyst house publishes an Asia-Pacific total for it. Cushman & Wakefield, Knight Frank and CBRE all report by market on incompatible boundaries, and none of them adds it up.
So I built one: 14 markets, mid-point where sources disagree, and it comes to roughly 10.5 GW live, excluding mainland China. The leading markets give the shape of it.
|
Market |
Live MW |
Basis |
|
India (national) |
1,819 |
Savills, MW IT +36.6% YoY |
|
Japan (national) |
1,800 |
C&W national |
|
Australia (national) |
1,500 |
AEMO, June 2026 |
|
Singapore |
1,118 |
Knight Frank |
|
Johor |
1,110 |
C&W and Knight Frank agree |
|
…9 more markets |
3,184 |
Hong Kong to Batam |
|
Klang Valley + secondaries |
not counted |
No published figure exists |
|
Total |
≈10,531 |
±10%, and understated |
Table 1. Author’s build-up across 14 markets; full table and per-market sources on request. Excludes Klang Valley and untracked secondaries, which have no published figure, so the total understates rather than overstates.
Treat that as a working estimate, not a fact: the error band is real at ±10 percent, wider in the markets where only one source reports, and it counts Klang Valley as zero because nobody publishes a figure for it. I would rather show a derived number with its workings and its limits than repeat a published one that answers a different question.
The full shape follows from it. Live and operating: about 10.5 GW, 28 percent of the eventual build-out. Under construction: 4.8 GW, 13 percent. Planned only: 21.7 GW, 59 percent. If every announcement lands, eventually around 37 GW, roughly three and a half times today’s live base. The headline pipeline is simply the second and third of those added together: everything not yet built.
Not all pipeline is equal
The aggregate hides how differently each market’s announcements are likely to arrive, and vacancy is the cheapest proxy for it. Regional colocation vacancy sits at 10.3 percent, but Johor is at 0.7 and Greater Seoul at 1.1, while Bangkok is at 23.3 and Jakarta at 22.5, the first two absorb capacity as fast as it lands, the second two are building well ahead of demand. North Asia has a different brake again: TEPCO is holding roughly 15 GW of connection applications against eight-to-ten-year lead times, Korea has approved four of 195 grid applications, and Malaysia has around 7,100 MW of signed electricity agreements against roughly 850 MW of actual load, grid positions being sat on, not buildings anyone intends to raise on that timetable.
Two clocks, not one
Getting the volume wrong costs money; getting the timing wrong costs more, because it decides what you build and when. There are two clocks running, and most capacity plans I see are set to the wrong one.
|
Window |
Wave |
What drives it |
|
2026–2028 |
Memory-led early harvest — now |
DRAM contract prices +93–98% QoQ in Q1 2026; NAND +70–75%. Hyperscalers pulling decommissioning forward to harvest DDR4. Iron Mountain and Sims both near 70% YoY ITAD growth. |
|
2028–2031 |
First true APAC decommissioning wave |
The 2023–25 build cohort reaching end of 5–6 year life |
|
2029–2033 |
Liquid-cooled AI rack retirement |
GB200/GB300-class racks; de-manufacture over shred |
Table 2. Author’s framing; drivers from TrendForce (memory pricing) and operator disclosure.
What is moving through the market right now is memory and drives out of conventional fleets, pulled forward by a price spike, not AI hardware. AI racks are a 2029-and-later story, and by then the handling requirements are different enough that today’s equipment will not serve them.
Size a facility off the 26.5 GW pipeline figure and you are building for 2031 with 2026 money.
The practical read is narrow and I would stake it: underwrite the 18 percent that is actually under construction and treat the rest as an option; weight each market by vacancy rather than by its headline; and build for the memory wave that is here, not the AI-rack wave that isn’t. The one number that would make all of this precise, tonnes of equipment per megawatt of retired capacity, is not published anywhere, which is exactly why three or four calibrated jobs would be worth more than any market report.
The ≈10.5 GW live base is derived by the author from 14 published market figures, ±10%, and understated by the exclusions above; the two-wave framing is a reading of published depreciation policy, memory pricing and operator disclosure, not a published forecast. C&W’s H2 2026 update, due around February 2027, will reset every figure here.
If you are carrying a capacity assumption built off the pipeline figure, for a facility, a hire plan, an investment case, do you know your own exposure to the 82 percent that is still on paper?
Sources
Cushman & Wakefield, APAC Data Centre Update H1 2026, 26,455 MW pipeline; 4,764 MW under construction; 21,691 MW planning.
Knight Frank Data Centre Atlas 2026; CBRE Global Data Center Trends 2026, per-market live capacity.
Savills; AEMO (June 2026); Shulman Advisory (TEPCO queue), market figures in the build-up.
TrendForce, 2Q26 DRAM/NAND contract prices.
Author’s live-base derivation across 14 markets, full table and sources on request.